
Quarterly Investment Letter
Preparing, not predicting
 Russell E. Lundeberg Jr., CPAPrincipal & Chief Investment Officer
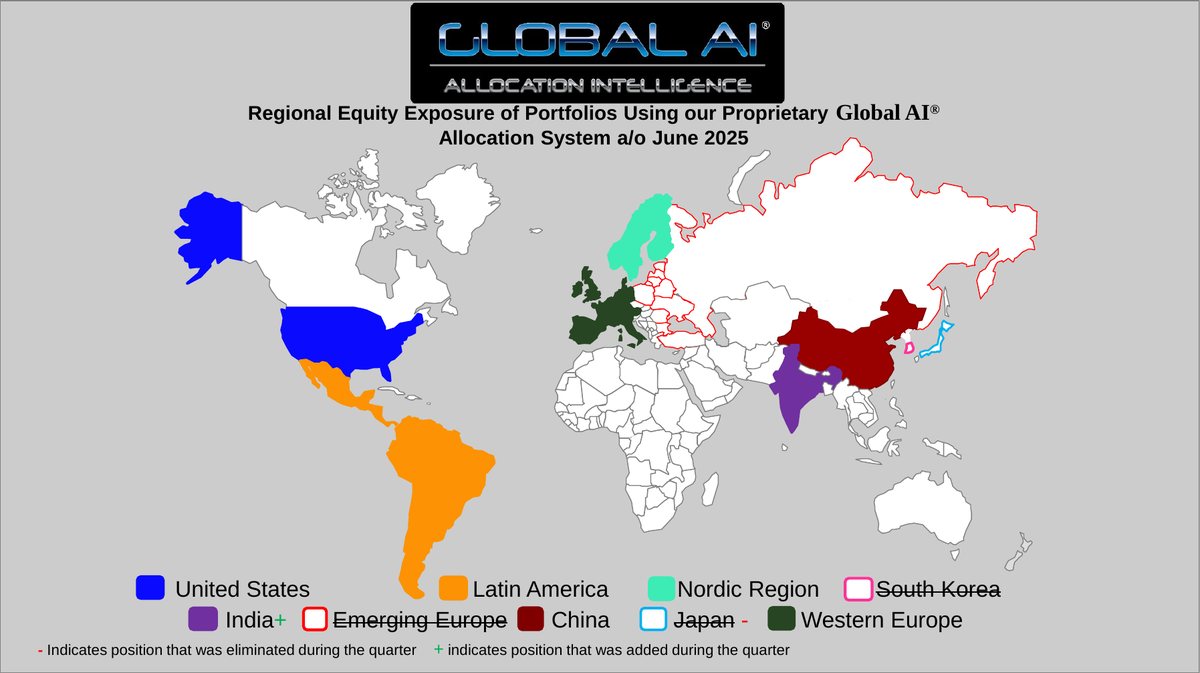
In most quarters, I typically send a short “market recap” message looking back at the previous three months in the markets. This quarter, I want to do something a little different by looking ahead. Not to make predictions — we don’t waste our time with that sort of thing here at Barrett Capital— but to mentally prepare ourselves for various possibilities. The more prepared we are, the easier it will be to maintain a long-term perspective rather than overreact to headlines.
To that end, let’s look at some of the storylines my team and I are following that could have an impact on the markets in the second half of the year.
To understand where we are, it’s always helpful to understand where we’ve been. So, in this letter, let’s do a quick recap of why markets performed the way they did in Q2. Then, I’d like to share why volatility is a feature, not a bug, of investing.
Tariffs: Back in April, the sweeping slate of tariffs enacted by the Trump Administration sent markets into a tailspin. Many of those tariffs were eventually canceled or suspended, and markets normalized. Since then, investors have entered into a kind of “worst is over mindset.” As many tariffs — which were originally suspended until July 9 — were further pushed back into August, the markets have continued to climb, unaffected by trade war fears.
In recent weeks, however, President Trump has again begun suggesting the possibility of new tariffs against various countries, and many trade deals have yet to materialize.1 Furthermore, many of the “Liberation Day” tariffs announced back in April that were subsequently paused are set to go into effect in August.
If tariff troubles begin rising again, it will be interesting to see whether investors react negatively, or whether the idea of tariffs has been normalized to the extent that it doesn’t really provoke a strong reaction. Either way, we should prepare ourselves for tariffs to continue influencing the pulse of the markets moving forward.
Inflation: One reason tariffs make both economists and investors nervous is because they can stoke inflation. Since many tariffs have been suspended or were never enacted, inflation has remained low for the year, but there are signs the tariffs that are in play are finally starting to have an effect. Consumer prices rose by 0.1% in May, and a further 0.3% in June, raising the overall inflation rate to 2.7% over the past twelve months.2 Those aren’t huge increases, but the fact that they apply to a wide variety of goods suggests that companies are now passing on the cost of tariffs to customers.
For investors, this matters because it has a direct impact on…
Interest Rates: The task of fighting inflation belongs to the Federal Reserve, which has a mandate to stabilize prices. The Fed’s ability to do this largely rests on its ability to drive interest rates.
President Trump has been very vocal about his desire for the Fed to lower interest rates quickly and significantly to help stimulate the economy. The Fed has been resistant to that idea, however, preferring to see how tariffs will affect inflation first. If inflation does continue to climb, it’s extremely unlikely the Fed will lower rates any time soon. Depending on how things go, it’s even possible the Fed could raise interest rates again.
D.C. Drama: Due largely to his frustration with higher interest rates, President Trump has frequently criticized the Fed’s chairman, Jerome Powell. On several occasions, the president has even suggested he might fire Powell.3 (At other times, he has also said he has no intention of doing so.)
Under normal circumstances, this sort of beltway drama is interesting only to other politicians — but the idea of a president firing the chairman of the Federal Reserve is anything but normal. You see, the Fed has historically functioned as an independent central bank, meaning its decisions do not need to be approved by either the president or Congress. Why does that matter? Because it gives the Fed freedom to accomplish its mission of maximum employment and stable prices during times of economic stress without having to seek approval first. It also has historically shielded the Fed from being overly influenced or controlled by other factions in Washington. In other words, it enables the Fed to focus on policy over politics.
Whether President Trump can legally fire Powell is an open question. The reason this could affect the markets, though, is because it would signal that the Fed’s independence is effectively over. That, in turn, would change everything about how investors expect the Fed to act when it comes to monetary policy. In other words, it would throw a major wrench of uncertainty into the markets. And uncertainty, as we know, is ultimately what causes volatility.
Some of these storylines may have a significant impact on the markets. Others may be complete nonfactors. The ultimate takeaway we must remember is to avoid overreacting to any of them. Remember: While storylines like this can drive the markets for weeks, months, even quarters, we are investing for years.
As always, my team and I will continue to keep a close eye on Washington and Wall Street so you don’t have to. But if you have any questions or concerns as we move towards the end of the year, please don’t hesitate to let us know!
Sincerely yours,
Russell E. Lundeberg Jr., CPA
Principal & Chief Investment Officer
Barrett Capital Management, LLC
Sources
- “Trump intensifies trade war with threat of 30% tariffs on EU, Mexico,” Reuters (opens in a new tab)
- “Consumer Price Index Summary,” U.S. Bureau of Labor Statistics (opens in a new tab)
- “Trump says ‘maybe’ he’ll try to fire Fed chief,” CBS (opens in a new tab)
This communication is for informational purposes only and contains a description of some of the factors which Barrett Capital Management, LLC considers in forming its investment strategy at the time of publication. The information herein is subject to change without notice. This is not a solicitation to participate in any investment strategy. Past performance is no guarantee of future results. Reproduction or distribution of this material is prohibited and all rights are reserved.